Investment Scams: How They Work, Warning Signs and What to Do
Investment scams promise high, steady returns on fake platforms or unregistered deals. Learn the common types, the warning signs, how to check a firm, and what to do if you've paid.
 By Editorial Team
10 min read
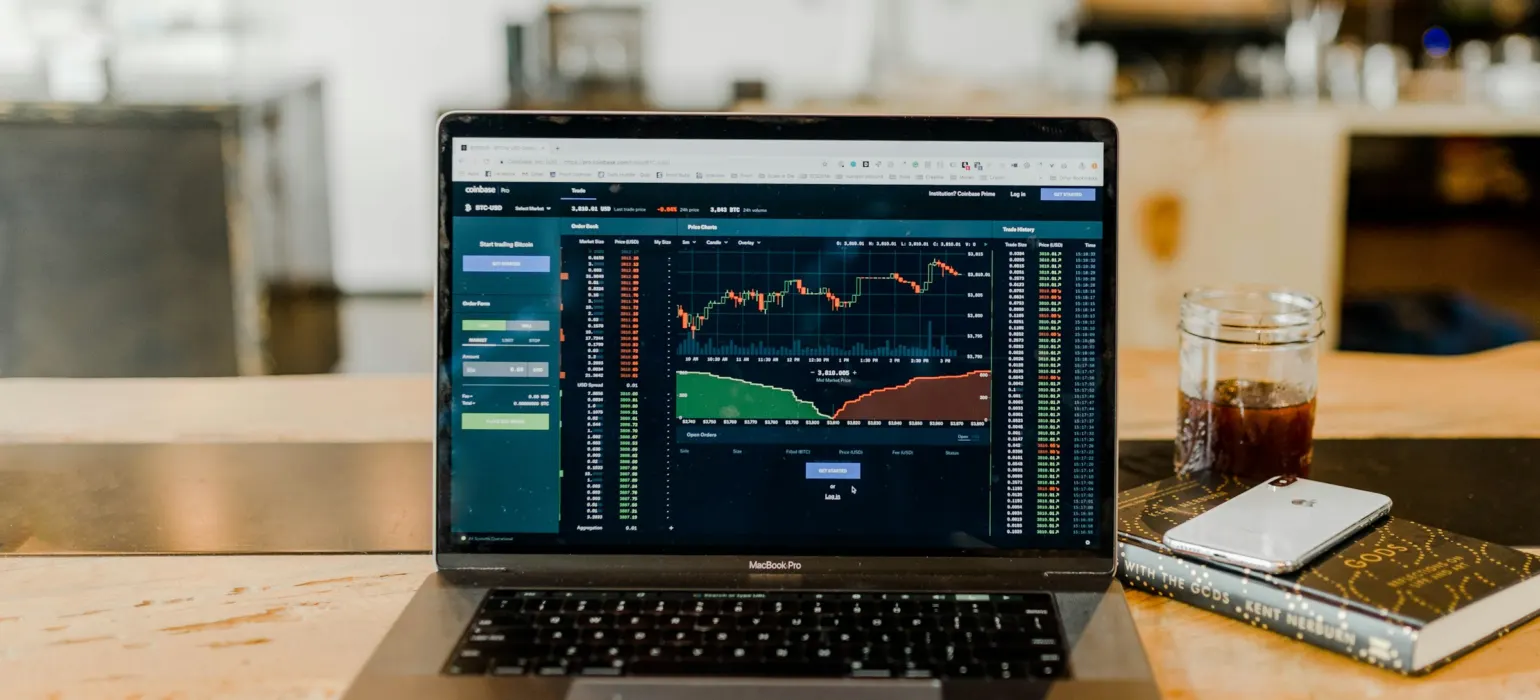
Investment scams persuade you to hand over money for an opportunity that doesn’t exist or isn’t what it seems, usually with promises of high, steady returns and little risk. The most common versions today start with a friendly stranger online who, after weeks of chatting, introduces a trading platform that shows fake profits. Before investing with anyone, look them up on the SEC’s Investor.gov and on FINRA BrokerCheck, and if you’ve already paid, stop sending money, call your bank and report it to the SEC, the FTC and the FBI’s IC3.
This guide explains how these schemes work and how to protect yourself. It’s general safety information, not investment advice. If you’re unsure about a real investment decision, talk to a registered financial professional you’ve found and checked yourself.
How investment scams usually work
Almost every investment fraud follows the same arc. The scammer builds trust, shows you proof that the investment is working, encourages you to add more, then makes it impossible to take your money out. The details change, but that pattern rarely does.
What makes these scams hard to spot is that the early stages feel normal. You may be able to withdraw a small amount at first. The dashboard may look professional. The person advising you may seem knowledgeable, patient and kind. None of that is evidence the investment is real.
Common types of investment scams
“Pig butchering” and relationship investment scams
The name comes from the scammers themselves: they “fatten up” a victim with attention before taking everything. It typically starts with a message that seems to be a wrong number, a match on a dating app, or a new contact in a professional group. Over weeks, sometimes months, the person becomes a friend or romantic interest. Only then do they mention how well they’re doing with a particular trading platform, and offer to show you how.
The platform is fake. The balance you see is just numbers on a screen the scammers control. When you try to withdraw, you’re told to pay a tax, a fee or a “verification deposit” first. Many of these schemes run through crypto, and our guide to crypto scams covers the crypto-specific details, including fake wallets and exchanges. If the relationship itself was the hook, the romance scams guide may also help.
Fake trading apps and platforms
Some scams skip the relationship and go straight to ads, social media posts or group chats promoting an app that “copies expert traders” or uses “AI trading bots.” The app may even be downloadable from what looks like a normal store listing. The key question is not whether the app looks polished, but whether the firm behind it is registered and whether you can independently confirm who runs it.
Investment clubs and group chats
Invitations to private groups on messaging apps, run by a “professor” or “mentor” who shares stock tips, are a common route. Early tips may seem to work. Later, members are steered into a specific stock or platform. Some of these are pump-and-dump schemes, where organizers push up the price of a thinly traded stock and sell to the people they recruited.
Ponzi schemes and “private” deals
A Ponzi scheme pays earlier investors with money from newer ones, so returns look consistent until new money dries up. These often come dressed as exclusive opportunities: pre-IPO shares, private real estate funds, promissory notes or “secret” trading strategies. They frequently spread through communities where people trust each other, such as churches, clubs or immigrant networks, which is known as affinity fraud.
Impersonation of real firms and advisors
Scammers copy the names, websites and credentials of real registered advisors and firms. Sometimes they pose as a well-known investor or use a deepfake video of a celebrity endorsing a product. A name that checks out on a registration database doesn’t help if you’re actually talking to an impostor, so always contact the firm through details you find yourself.
Warning signs of an investment scam
- High returns with little or no risk. Real investments carry risk. A promise of guaranteed or unusually steady returns is one of the clearest warning signs regulators describe.
- Pressure to act now. “The window closes tonight,” “only a few spots left,” or anger when you want time to think.
- Someone you met online brings up investing. Especially if you’ve never met in person and they’ve avoided video calls.
- Payment in crypto, wire transfer or gift cards. Or instructions to send money to a personal account rather than a regulated firm.
- You can’t withdraw without paying first. Taxes, fees, “release” charges or “anti-money-laundering deposits” are a sign the money is already gone.
- Secrecy. Being told not to discuss it with family, your bank or a financial advisor.
- Unregistered sellers. The person or firm doesn’t appear on Investor.gov, BrokerCheck or with your state securities regulator.
How to check an investment or advisor before you pay
Checking takes a few minutes and costs nothing. Do it before any money moves.
- Search the SEC’s Investor.gov. Its “Check Out Your Investment Professional” search shows whether an individual or firm is registered and whether there’s disciplinary history.
- Search FINRA BrokerCheck. It covers brokers and brokerage firms, including past complaints and actions.
- Contact your state securities regulator. Some advisors register with the state rather than the SEC, and state regulators can tell you whether an offering is registered or exempt.
- Confirm you’re dealing with the real person. Find the firm’s phone number on its official website, which you type in yourself, call it and ask whether the person works there.
- Search the name alongside words like “scam,” “complaint” or “fraud.” Also look for SEC investor alerts and state warnings about the platform or scheme.
Registration is a minimum, not a seal of approval. A registered professional can still recommend a bad investment, but an unregistered one selling you securities is a serious red flag.
What to do right now if you think it’s a scam
- Stop sending money. Don’t pay any “final” fee or tax, and don’t try to win back losses by depositing more.
- Stop contact. You don’t need to confront the person or explain yourself. Just stop replying.
- Call your bank or card issuer. Use the number on your card or in the official app, say it’s fraud, and ask them to stop or recall any pending payments.
- Contact the exchange or payment service you used. If you bought crypto and sent it on, contact the exchange through its official app or website.
- Secure your accounts. If you shared passwords, ID documents or gave remote access to your device, change your passwords, turn on two-factor authentication and read our guide to what to do if your identity is stolen.
- Save the evidence. Screenshots of chats, profiles, the platform’s website and app, transaction IDs, wallet addresses and bank records.
Where to report an investment scam
- The SEC, through its official tips and complaints portal on sec.gov, for securities fraud, fake trading platforms and unregistered offerings.
- The FBI’s Internet Crime Complaint Center at ic3.gov, especially for online and crypto investment fraud. Include wallet addresses and transaction details.
- The FTC at ReportFraud.ftc.gov.
- Your state securities regulator, which can act on local sellers and unregistered offerings.
- FINRA, if a broker or brokerage firm was involved.
- The platform where you were contacted, such as the dating app, social network or messaging service, and the app store if the fake app was listed there.
If you’re not in the US, or want every option in one place, our guide on how to report a scammer lists reporting routes in several countries.
Can you get money back from an investment scam?
Sometimes, but it depends almost entirely on how you paid and how quickly you act.
| How you paid | What you can try |
|---|---|
| Credit or debit card | Ask your card issuer about a dispute or chargeback as soon as possible. |
| Bank transfer or wire | Report it to your bank as fraud straight away. A recall is sometimes possible if the money hasn’t moved on, but wires are often impossible to reverse. |
| Payment apps | Report the payment in the app and to your bank. Protections for payments you authorized are often limited. |
| Cryptocurrency | Usually irreversible. Report to the exchange and to IC3 with wallet addresses, in case funds can be traced or frozen. |
After a loss, expect to be contacted by people who say they can recover your money for a fee, sometimes claiming to be lawyers, regulators or “blockchain investigators.” In most cases this is a second scam aimed at people who’ve already been hurt. Our guide to recovery scams explains how to recognize them.
A worked example
This is an illustrative scenario, not a real case. Priya, a pharmacist, joins a professional networking group and starts chatting with a friendly member who says he works in finance. Over five weeks they talk most days. He mentions he’s been doing well with a trading app that follows a “market signal,” and offers to walk her through a small trade.
Her first deposit grows quickly, and she’s allowed to withdraw a small amount, which reassures her. She adds more. When she asks to withdraw a larger sum, the app says her account is frozen until she pays a “capital gains verification fee.”
- Priya searches the platform’s company name on Investor.gov and BrokerCheck and finds nothing. She also finds an online warning about a similar-sounding app.
- She stops replying and pays nothing more.
- She calls her bank using the number on her card and reports the transfers as fraud.
- She files reports with the SEC, IC3 and the FTC, including the app’s web address and her transaction records.
- A week later a “fund recovery attorney” emails her. She recognizes the pattern and reports that too.
Not sure where to start?
Get a free audit of your search results and review profiles, with a prioritized fix list.
Get a free auditHow to protect yourself next time
- Keep investing and relationships separate. If someone you met online, however close you feel, brings up an investment, treat it as a stop sign.
- Check registration every time. Investor.gov, BrokerCheck and your state regulator, before any money moves.
- Use accounts you opened yourself at firms you found independently, not through links someone sent you.
- Take your time. Real opportunities survive a week of thinking and a conversation with someone you trust.
- Talk it through. A family member, a friend or a fee-only advisor you checked yourself can often spot what’s hard to see from inside the conversation.
Common mistakes to avoid
- Paying the “withdrawal fee.” It’s the most common way losses grow.
- Trusting the dashboard. A balance on a scammer’s site is not money you own.
- Waiting out of embarrassment. Speed matters for bank recalls. Scammers are skilled professionals, and being caught says nothing about your intelligence.
- Posting accusations with someone’s photo. Scammers often steal real people’s pictures. Report the account instead.
When scammers use your name or business
If you’re a registered advisor or run a financial business, scammers may clone your website or profiles to sell fake investments. Report each fake account as impersonation, warn clients through your official channels, and tell your regulator. Our guide on online impersonation covers the steps, and the financial advisor reputation page explains how we can help if scam complaints start showing up under your name.
Losing money this way can be distressing. If it’s affecting your sleep or wellbeing, our help resources page lists places to get support.
Frequently asked questions
What is the most common investment scam right now?
Relationship-based schemes, often called pig butchering, are among the most widely reported: a stranger builds a friendship or romance online over weeks, then introduces a fake trading platform that shows profits you can’t withdraw.
How do I check if an investment firm is legitimate?
Search the firm and the individual on the SEC’s Investor.gov and on FINRA BrokerCheck, and contact your state securities regulator. Then confirm you’re dealing with the real firm by calling a number from its official website that you found yourself.
Who do I report investment fraud to?
Report it to the SEC through its tips and complaints portal, to the FBI’s IC3 at ic3.gov, and to the FTC at ReportFraud.ftc.gov. Also tell your bank and your state securities regulator, and report the account on the platform where you were contacted.
Should I pay a fee to withdraw my profits?
No. Legitimate platforms deduct fees from your balance; they don’t demand a new deposit before releasing your money. A request like this is a strong sign the platform is a scam and the balance isn’t real.
Can a lawyer or recovery company get my money back?
Be very careful. Anyone who contacts you offering to recover scam losses for an upfront fee is usually running another scam. If you want legal advice, find a lawyer yourself through your state bar, and never pay in crypto or gift cards.